California home loans for people the bank's checklist misses. Fill in the blanks and see your way through.

, I'm , and I need .

Tap any yellow word to change it.

EXIT 1

A bank statement or P&L loan

Your tax return shows what's left after write-offs. These loans look at the deposits going into your business instead, using 12 or 24 months of bank statements or a CPA-prepared profit and loss statement.

Try the bank statement calculatorWatch how it works (54 sec)

What it takes

  • 12 or 24 months of bank statements, or a CPA-prepared P&L
  • Your credit, the property and your down payment are still reviewed
Want Ken to look at it?

Ken calls or texts you back, the same business day when possible. You won't need any documents yet.

Qualification is subject to investor guidelines. No rates are quoted here. Prefer to text? 949-244-6405

Which exit is yours?

Each of these loans exists for a reason the bank's checklist can't see. Here's what each one is for, in plain English, and what it takes.

EXIT 1

Self-employed

Bank statement P&L

Qualify on what your business actually brings in.

Your tax return shows what's left after write-offs, which is why a bank can say you earn too little. These loans look at the deposits going into your business instead.

Bank StatementP&L
Watch: how bank statement loans work (54 sec)

What it takes

  • 12 or 24 months of bank statements, or a CPA-prepared profit and loss statement
  • Your credit, the property and your down payment are still reviewed
EXIT 2

Rental property

DSCR

Let the rent qualify the loan.

For investment property, a DSCR loan compares the property's rent to its monthly payment. Your personal income and tax returns aren't the deciding factor.

DSCR
Watch: how DSCR loans work (54 sec)

What it takes

  • The rent: a current lease or the appraiser's rent estimate
  • The full monthly payment, including taxes, insurance and any HOA
  • An investment property, not the home you live in
EXIT 3

Home equity

Second TD

Get cash out without giving up your low rate.

A second trust deed is a separate loan behind your current mortgage. Your first loan, and its rate, stay exactly as they are.

Second TD
Watch: how a second TD works (44 sec)

What it takes

  • Equity left in the home after your current first loan
  • Your current mortgage statement
  • Income documented in a way that fits your situation
EXIT 4

Turned down

Ken looks again

A bank's no is usually one checklist's no.

Banks mostly offer standard loans with fixed rules. Ken works only with loans outside those rules and looks at the whole picture, including business-purpose and asset-based options and short-term bridge loans.

Stated / No-DocBridge Takeout
Watch: bridge takeout loans (32 sec)

What it takes

  • The reason you were turned down, if you have it
  • A few basics about the property and what you're trying to do

How it works

Four steps, and you talk to the same person the whole way.

  1. Tell Ken your situation

    Fill in the sentence above, or text 949-244-6405. A few basics are enough. No documents yet.

  2. Ken reviews it

    The same business day when possible. He'll ask the two or three questions that actually matter for your file.

  3. Documents go through a secure link

    If there's a path, you get a secure upload link for your loan. Never email your documents or send them through a website form.

  4. You get a straight answer

    Terms when there's a path. A clear reason when there isn't.

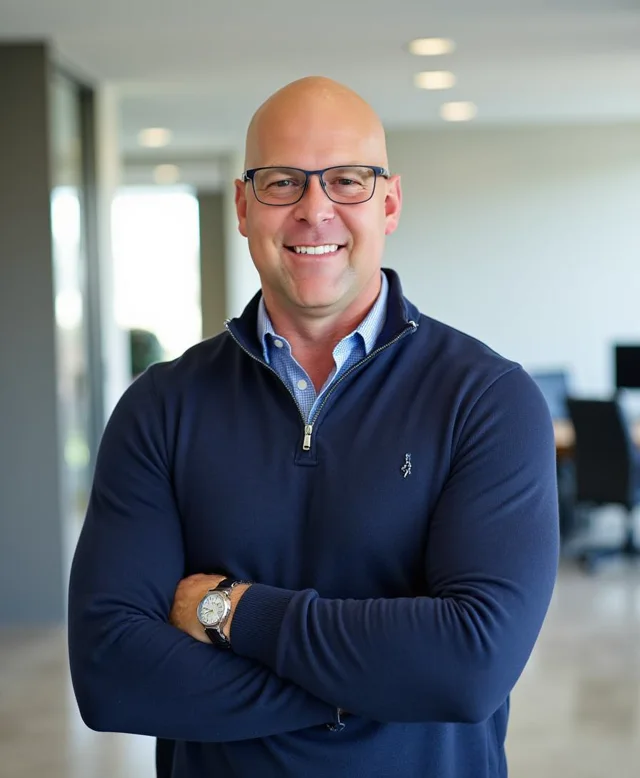
Ken Schisler

You work with Ken directly.

Ken Schisler is a mortgage broker in Costa Mesa with more than 20 years in lending. AltDoc Loans does only the loans that don't fit the standard checklist, so your file gets someone who handles them every day.

202579 loans funded$79.2M

NMLS #328993 CA DRE #01429613 Look up Ken's license

Not sure which exit? Ask Ken.

Find your exit Text Ken